There is no single public mortgage rule that guarantees a loan to every foreign buyer. Korean lenders assess the borrower, income evidence, residence status, property and funding source, so a nonresident should get a written pre-screen from the lender before signing a property contract.
간단 요약
- Approval and loan size are lender-specific; do not budget from an online percentage.
- Ask about residency, income currency, repayment account, property and collateral rules.
- Foreign-exchange reporting may apply to a nonresident’s purchase funds.
1. What determines whether a lender will review your case?
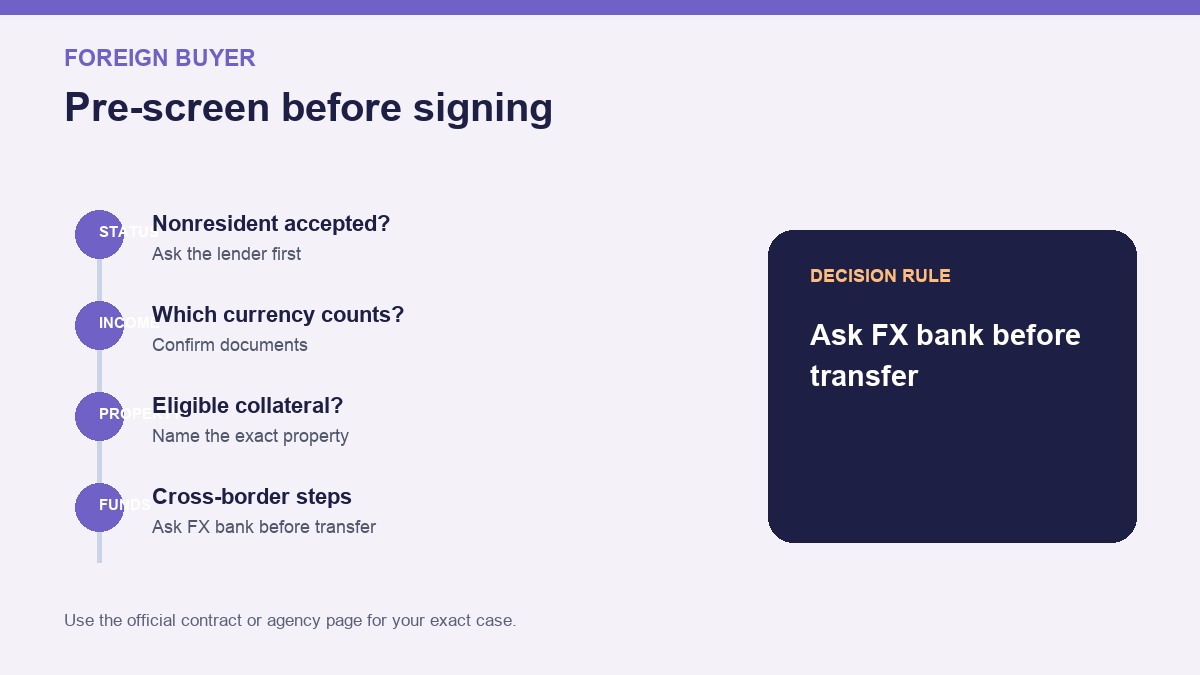
The bank’s underwriting policy—not a single foreigner-wide threshold—sets the application route. Before paying a deposit, ask whether the bank handles nonresident foreign borrowers, what income it accepts, and whether the property and loan purpose qualify for review.
2. Why does foreign income need special checking?
A lender may need translated income records, tax returns, employment confirmation and evidence that income can be transferred for repayment. Whether those records are accepted, and how exchange-rate risk is treated, depends on the bank and the applicant.
Ask the lender to state which documents need translation or notarization and whether a Korean co-borrower or guarantor changes the application. Do not treat a broker’s estimate as loan approval.
3. What if the money comes from overseas?
InvestKOREA explains that nonresident foreign buyers can have separate foreign-exchange reporting steps when bringing funds from abroad or withdrawing funds for a Korean property purchase. The bank may require contract, valuation and registration documents to support the transaction.
Tell the foreign-exchange bank how the purchase will be funded before sending money. Keep the remittance trail, loan offer and contract consistent; changing the funding route later can add paperwork.
5. Official sources
- InvestKOREA: nonresident real-estate acquisition and procedures
- Bank of Korea foreign-exchange transaction guidance
🌐 공식 사이트 바로가기
✅ 결론
1) Send the bank a borrower and property summary, 2) get its accepted document list, 3) obtain a written indicative review with assumptions, 4) confirm foreign-exchange steps, then 5) have a local professional review the contract’s financing contingency.
FAQ — 자주 묻는 질문
Q1. Is there a standard down-payment percentage for foreign buyers?
This research did not find a universal official percentage that applies to all foreign borrowers and properties. Ask the lender to pre-screen your exact case and state its assumptions.
※ Checked October 1, 2026. Terms can change and vary by person, provider or transaction; confirm the current rule with the linked official source before acting.